How to Automate MeridianLink
MeridianLink automates the lending pipeline itself: a decisioning engine with configurable rules, Dynamic Workflow moving applications between pipelines, and notices about outstanding stipulations. What still takes a person is fetching evidence from payroll verifiers, titling services, insurers and dealer portals. An agent like WebRun does that gathering, and the credit decision stays with your underwriter.
 Written by
Rosa Lindqvist
Operations editor
 Reviewed by
Devon Ruiz
Workflow engineer
MeridianLink is where a member becomes a borrower
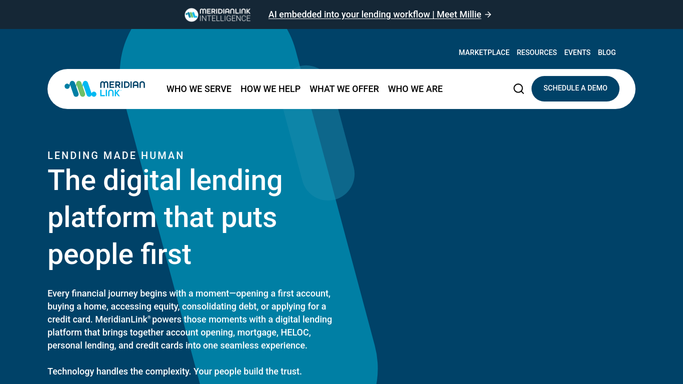
MeridianLink is the software a credit union or community bank uses to turn an application into an account or a loan. Staff meet it under several names: MeridianLink Consumer for consumer lending, MeridianLink Opening for new deposit accounts, MeridianLink Access for the form a member fills in on the website, MeridianLink Mortgage for home loans, and DecisionLender behind indirect deals from a dealership.
That makes it the front door. Someone applies for a used car loan at nine at night from a phone, and by morning it is a file with a credit report attached, a stage in a pipeline, a list of stipulations and a loan officer's name against it.
It is also the system examined hardest. A lending decision has to be consistent, documented and explainable, because a regulator can ask why this member got a rate and that one got a decline, and the answer has to be in the record.
An application stalls on paperwork the member has to go and find
The processing work around a loan is mostly not lending. It is asking people for things and then waiting.
A member uploads two of the four documents and forgets the rest, so somebody emails to ask again. Somebody logs into a payroll verification service to confirm income the applicant quoted from memory. Somebody opens the titling service to see whether the lien was perfected, then the insurer's portal for the binder, then the dealer's system for the buyer's order. Somebody requests a payoff quote from whichever lender holds the trade, because that figure moves daily.
Then the flood determination, then the fraud and screening results, each arriving from its own site.
None of that is judgement. It is a login, a search box and a number that has to end up in a field in MeridianLink. It also decides whether the member hears back today or on Thursday, and Thursday is how the loan goes to the dealership instead.
Decisioning is the fast part once the file is complete
MeridianLink automates a great deal of the lending process, and any institution should exhaust that before buying anything else.
Its decisioning engine runs configurable rules and visual logic trees, so a clean application is graded in seconds against the policy the credit committee approved, with standard decisioning for straightforward products and advanced decisioning where somebody wants layered logic. Dynamic Workflow moves applications into and out of configured pipelines on business rules, and notifies the applicant, the user or the dealership about a status change or an outstanding stipulation. Documents generate off the file and results sync to the core.
Every one of those acts on what has already reached the file. Decisioning grades the income figure once the income figure is in the field. The workflow chases a missing stipulation by sending a notification about it.
Neither can go and get the pay stub. When the stipulation is a document behind a login at an employer, a titling service, an insurer or a dealer's system, the platform's job ends at noticing it is missing and asking a human to fetch it. That request is where the file stops moving.
Verification work can be finished before the underwriter starts
The waiting in a loan file is nearly all fetching, and fetching runs perfectly well overnight.
Payoff quotes pulled from each lender's own site and written against the trade, so a deal is structured on a real number rather than an estimate that has already moved. Insurance binders confirmed on the carrier's portal the week before funding, not on the morning of it. Lien and title status checked against the state's own system, so nobody discovers on Friday that a perfection is still pending.
Then the quieter ones. Dealer portals worked at seven for applications that sat in somebody else's queue overnight. A business borrower checked against the secretary of state's register, so a dissolved entity or a name change surfaces before the note is drawn. The reason behind a decline gathered with its evidence, because an adverse action notice has to say something true.
The line here is the one every lender already draws. Collecting evidence, comparing documents and preparing a file can run unattended overnight. Grading the risk, approving the loan and releasing the money belong to a person whose name goes on it.
The approval still belongs to a person
So the fetching happens overnight and the decision waits for morning. That split is the entire point, and it is the only version of this a regulated lender could defend to an examiner.
WebRun is an AI agent that works a real Chrome browser, signed in as you. It opens the payroll verifier, the titling service, the dealer portal or the insurer, reads what each one says, and puts the result where MeridianLink can use it.
It runs on your schedule inside your own private environment, restricted to the sites you allow, and you can watch a run and stop it. Nothing is approved, declined, funded or sent to a member without a person reading it first.
The workflows below are already built, and each one names the systems it opens.
Questions people ask
Could this approve or decline a member's application?
No. It gathers and prepares, and it stops there. The credit decision, the counter-offer, the funding and the adverse action notice are all made and issued by your staff, working from a file that is complete rather than half empty.
Our examiners will ask about this. What do we show them?
A record of every run: which sites were opened, what was read, what was written to the file and when. It works inside a policy that names the allowed sites and takes no decisioning action, so the audit trail behind any approval is still your own.
Does this duplicate what our MeridianLink administrator already builds?
Very little of it. An administrator configures rules, logic trees, pipelines and notifications inside the platform. This does the part that cannot be configured anywhere, which is opening another company's website and reading the document the stipulation is asking for.
13 ready-made MeridianLink workflows
Each one names the apps it touches and the exact steps it takes. Open one to read what it will do, then turn it on.

Want one of these running on your own MeridianLink?
Show WebRun the process once and it will run it on schedule, in your own private browser environment.