How to Automate Floify
A Floify loan flow can run its own borrower notices, document requests and milestone updates, and on Encompass it pulls in conditions. Automating beyond that means reading what sits around each loan, such as wholesale lender portals, the appraisal site and document dates against the closing date, which an AI agent such as WebRun can do for the loan officer.
 Written by
Julian Adeniyi
Retail operations
 Reviewed by
Aiko Tanabe
Product researcher
Floify is the borrower's side of the loan file
Floify is a mortgage point-of-sale system: the branded portal where a borrower fills in the 1003, uploads paystubs and bank statements, signs disclosures and watches the loan move through its milestones. Independent mortgage banks, credit unions and community banks run the Lender Edition, and mortgage brokers the Broker Edition, which can serve as the broker's main LOS or sit beside one. Floify connects to LOS platforms such as Encompass, MeridianLink Mortgage, Byte and LendingPad.
Each application becomes a loan flow in the loan officer's pipeline, with a needs list of every document the loan still requires. Dynamic AI reads uploaded paystubs, W-2s and IDs and fills in the application from them. Real estate agents get a Partner Portal where they see where a loan stands, upload what they hold and, if allowed, create pre-approval letters within the limits the lender sets.
The loan officer lives in the pipeline, the processor in the needs list, and the borrower in the portal, usually on a phone after dinner. An operations manager sets up the milestone sets, email templates and business rules that decide what each borrower sees and when.
A loan flow stalls on the one document nobody chased
The borrower uploaded one of the two bank statements, and the March paystub will be too old by the June closing. A gift letter came back signed by the wrong relative. For the processor, each of those is a wait measured in days.
Other companies on the file add their own delays. The appraisal sits on the management company's portal. The title commitment went to the loan officer's inbox instead of the processor's. For a broker, a wholesale lender posted three new conditions in the lender portal overnight, and the rate lock it confirmed runs out on Friday, while nobody has yet checked whether the file can close by then. Then the buyer's agent rings twice a week for an update, and the loan officer finds out about the gap when the borrower calls to ask why nothing has happened.
Six automatic notices keep Floify's borrowers moving
Floify sends six automatic notices to borrowers: the Needs List email, the Add Document, Reject Document and All Docs Accepted notices, the Deadline Notice and the Idle Application notice, and every one but the Needs List email can be switched off. Business rules read the answers on the application and add the right document requests to the needs list. Milestone sets update the borrower and the agent as the loan moves and can sync milestones with the LOS.
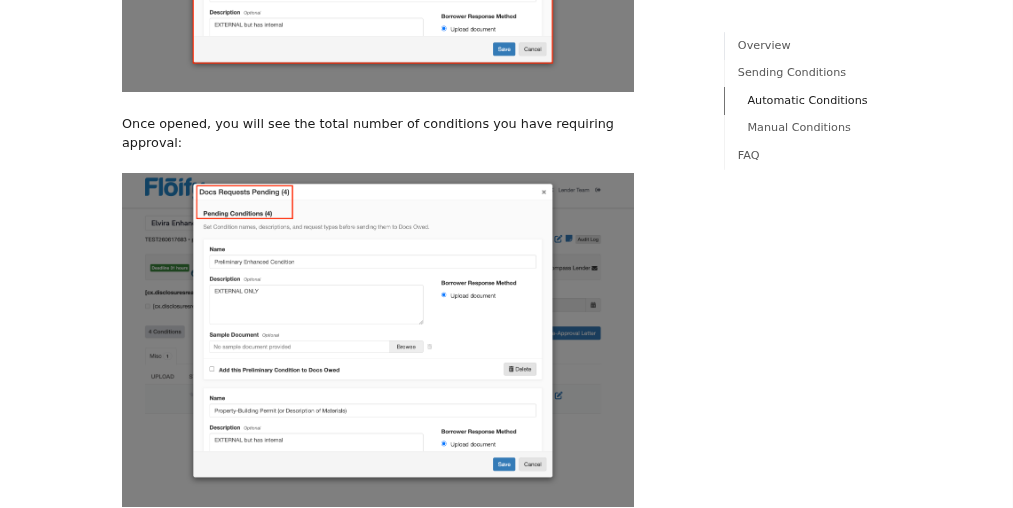
On Encompass, Floify pulls conditions marked Requested into the borrower portal as document requests, either straight away or after the loan team approves them in Conditions Pending Review. Brokers can run Desktop Originator and Loan Product Advisor together through Dual AUS and compare the results, and get pricing through LenderPrice.
A broker's wholesale lenders post their conditions and lock confirmations in their own portals, outside that Encompass sync. The appraisal status sits on the appraisal management company's site. Whether a paystub will still be acceptable at closing is a sum the processor does by hand, from its date and the closing date.
Fresh paystubs requested before the old ones age out
The processor could see, each week, every paystub and bank statement in the active loan flows that will be too old by the closing date, listed by borrower, with a request for fresh copies drafted in the loan officer's name.
At a broker, the processor could have each wholesale lender's overnight conditions set against the Floify needs list before the day begins, and add only the requests that are really missing. The loan officer could see the appraisal status and the lock expiry for every loan with open items, and a borrower who has not touched the portal for days could get a personal note in the loan officer's voice instead of another automatic reminder.
Each Friday the loan officer could go through the pre-approval letters more than a month old for buyers still shopping, and check the numbers before the buyer's agent sends an offer on one.
One morning check across Floify's pipeline and the wholesale lender portals
Each loan's conditions live in two places, the wholesale lender's portal and the Floify needs list, and comparing them takes a login to each and a few minutes per loan. WebRun is an AI agent that works a real Chrome browser; it opens the Floify pipeline and needs lists under a login the operations manager sets up, then the lender and appraisal portals, and lists each gap against its loan.
Credit pulls, AUS runs and rate locks cost money or commit the lender, and the agent starts none of them. Each borrower nudge is a draft in the loan officer's name, nothing reaches a borrower from the agent directly, and Floify's own notices carry on as configured.
The document refresh runs weekly against the stale-paystub problem, listing the documents about to age out and drafting the requests for fresh copies.
Questions people ask
Which wholesale lender portals can it check?
Any that open in a web browser under a login the broker gives it. The agent reads each lender's posted conditions and lock confirmation and sets them against the Floify needs list, so the processor sees only what is new.
Will borrowers get messages from it directly?
No. Every nudge and refresh request is drafted in the loan officer's name and sent by the loan officer. Floify's own automatic notices keep going exactly as the operations manager configured them.
Where does appraisal status come from?
From the appraisal management company's portal, under the login the processor already uses there. The agent reads the status of each open appraisal and lists it against its loan for the loan officer.
Who creates the pre-approval letters?
The loan officer, or a real estate agent given permission in the Partner Portal, within the loan limits and letter template the lender sets. The agent can list letters more than a month old for buyers still shopping, so the loan officer checks the numbers before an offer goes in.
Sources
- Floify Broker Edition Describes Floify's point-of-sale portal, 1003 application, Dual AUS with Desktop Originator and Loan Product Advisor, automated milestones, emails and SMS for borrowers and referral partners, the LenderPrice integration, Mortgage Call Reports, and that the Broker Edition can serve as the main LOS or enhance an existing one.
- Change the idle application reminder cadence | Floify Help Center Explains Idle Application Reminders sent automatically on a chosen cadence to prompt borrowers to finish incomplete applications, with optional blackout days.
- Company milestone sets | Floify Help Center Covers milestone sets applied by business rules, milestone updates sent to all parties, and Milestone Sync with the LOS.
- Floify Integrations Lists Floify's integration partners, including LOS platforms such as Encompass, MeridianLink Mortgage, ByteSoftware, LendingPad and Vesta, plus credit, verification, pricing and CRM providers.
- Set Up Encompass Conditions to Floify Document Requests | Floify Help Center Explains that Floify pulls Encompass conditions marked Requested into the borrower portal as document requests, either automatically or after review in Conditions Pending Review.
- Floify Email Overview | Floify Help Center Lists the automatic borrower notifications (Needs List, Add Document, Reject Document, All Docs Accepted, Deadline and Idle Application) and the option to send each automatically, manually or not at all.
- Totally Dynamic. Totally Floify. | Floify Describes Dynamic AI classifying uploaded borrower documents, extracting key data and pre-filling the application.
- 3 features that wow agents | Floify blog Describes the Partner Portal, where real estate agents see loan status, upload documents and, with permission, create pre-approval letters within the lender's loan limits and template.
- Floify: mortgage point-of-sale software Describes Floify as mortgage point-of-sale software for mortgage brokers, independent mortgage banks, credit unions and regional and community banks, with Lender and Broker Editions.
4 ready-made Floify workflows
Each one names the apps it touches and the exact steps it takes. Open one to read what it will do, then turn it on.
Want one of these running on your own Floify?
Show WebRun the process once and it will run it on schedule, in your own private browser environment.